Introduction
Blockchain technology is playing an increasingly important role in modern digital platforms and information systems. It is often connected with Bitcoin and other cryptocurrencies, but its use is much wider than digital money. Companies, banks, healthcare organizations, supply chains, governments, and technology providers are exploring blockchain because it can help people share and verify information without depending on one central database.
For someone new to technology, the word “blockchain” can sound complicated. Terms such as blocks, nodes, hashes, miners, validators, consensus, and distributed ledgers may make the subject difficult at first. For beginners, blockchain becomes much easier to understand once its process is broken down into clear steps. In simple terms, it records information in separate blocks, connects those blocks together, and keeps the information available across multiple computers within the network.
This guide explains how blockchain works in simple English. It covers the basic structure of a blockchain, how transactions are created and verified, how blocks are connected, how network participants agree on new information, and why changing old records is difficult. It also explains blockchain in cryptocurrency, finance, healthcare, and other industries so beginners can understand where this technology can be useful.
What Is Blockchain?
Blockchain is a digital system that organizes and records information by placing data into connected groups known as blocks.These blocks are connected to one another in a specific order, creating a chain. Instead of keeping all data on one central server, a blockchain distributes copies of its records among many computers connected to the network.
Blockchain technology relies on a shared ledger that keeps records across multiple computers. In simple terms, a ledger is a record that keeps track of transactions or other types of information. With a distributed ledger, this record is shared among several computers connected to the same network instead of being stored in one central location. When the network approves new information, the participating computers update their records to keep them synchronized.is accepted, the network updates the relevant copies according to its rules.
Unlike a traditional database, a blockchain is designed to make records difficult to change after they have been confirmedHowever, blockchain networks are not all built the same way, so their ability to resist changes depends on their design, security features, and network structure.However, changing an established record generally requires overcoming the network’s security and consensus mechanisms.
The technology became widely known through Bitcoin, but blockchain itself is not the same thing as cryptocurrencyCryptocurrency is a well-known use of blockchain, but the technology has many other purposes. Blockchain Blockchain networks can be designed to store, organize, and authenticate a wide range of digital data.
How Blockchain Works Step by Step
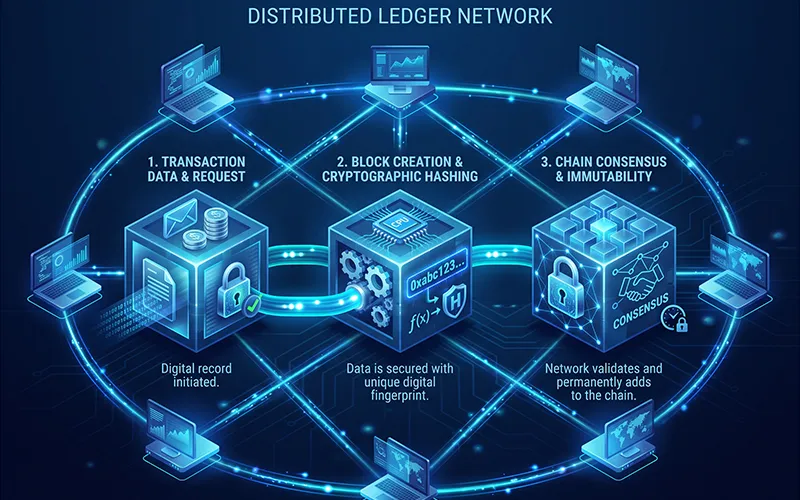
The process can look complicated when technical terms are introduced, but the basic sequence is quite logical. A transaction or piece of information is first created, then shared with the network. Once the transactions pass the network’s checks, they are grouped into a new blockOnce the network approves the block, it becomes part of the existing blockchain and is linked with the records that came before it.
Step 1: A Transaction Is Created
Everything starts when someone creates a transaction or submits information to the blockchain network. In a cryptocurrency network, this might mean one person wants to send digital coins to another person.
The transaction normally contains information such as the sender, receiver, amount, and other data required by the network. The sender also uses a private key to digitally sign the transaction. This signature helps prove that the transaction was authorized by the owner of the relevant digital assets.
When a transaction is submitted, it reaches the blockchain network, allowing connected computers to receive the details and verify them before further processing.
Step 2: The Network Receives the Transaction
Once a transaction is submitted, it is sent across the blockchain network, where connected computers receive the request and check its details against the network’s rules before it can be accepted.
The network checks the sender’s available balance and confirms that the transaction has been digitally authorized.If the transaction fails important checks, it can be rejected.
This stage is important because blockchain does not simply accept every piece of information that someone sends. The network uses predefined rules to determine whether a transaction can move forward.
Step 3: Transactions Are Verified
The next stage is verification. The method used to verify transactions can vary from one blockchain network to another.Some blockchains rely on miners through Proof of Work, while others use validators through Proof of Stake to confirm transactions.
During verification, the network checks whether the transaction follows the rules. It may confirm that the sender has the necessary balance, that the signature is correct, and that the transaction does not conflict with previously confirmed information.
The network first verifies a transaction, and once approved, it is added to the blockchain’s permanent record.
Step 4: Verified Transactions Are Grouped Into a New Block
Once the network confirms that transactions meet its rules, the approved transactions are organized into a new block. A block works like a container that stores several verified transactions at the same time. Instead of adding every transaction separately to the blockchain, the network groups related transactions together and records them as one block. Along with the transaction details, the block also includes technical data that links it with the previous and next parts of the blockchain, helping maintain the chain’s structure and security. it in the chain. This is one reason blockchain is called a “blockchain”: information is organized into blocks, and those blocks are linked together.
Step 5: The Network Reaches Agreement
For a new block to join the blockchain, network participants must first verify the information and agree that it follows the system’s rules.This is called consensus.
Consensus is necessary because there may be many computers operating in different locations. They need a common method for deciding which transactions and blocks are valid.
Blockchain uses different consensus approaches, including Proof of Work and Proof of Stake, to check transactions and decide which blocks can become part of the blockchain. Although each method follows a different process, both help the network reach a shared decision without depending on a single central authority.
Step 6: The New Block Becomes Part of the Blockchain
Once the network approves a new block, it is added to the existing blockchain. The block is securely connected to the one before it through cryptographic data, helping maintain the chain’s integrity.
Every block is linked to the one that came before it, creating a continuous chain of records.This creates a connection between old and new records. If someone tries to change information inside an earlier block, the cryptographic relationship between the blocks can be affected.
This is a major reason blockchain records are considered difficult to alter after confirmation.
Step 7: The Network Updates Its Records
Once a block is accepted, participating computers update their copies of the blockchain according to the network’s rules. The new information becomes part of the shared record.
The transaction is now considered confirmed, although the number of confirmations and the meaning of “final” can differ between blockchain networks.
This complete process provides a practical how blockchain works step by step visual idea: create a transaction, broadcast it, verify it, place it into a block, reach consensus, connect the block to the chain, and update the network.
What Is a Hash in Blockchain?
A hash can be compared to a digital fingerprint for a piece of data. A hashing function takes input and produces an output that represents that input.
For example, if a blockchain stores certain transaction information and generates a hash from it, changing even a small part of the underlying information can produce a different hash. This makes hashing useful for detecting changes.
Blockchain systems use hashes in several ways. They can help connect blocks, identify data, and support the security of the network. Hashing is therefore an important part of how blockchain works, although hashing alone is not responsible for the complete security of a blockchain.
The actual security model depends on several components working together, including cryptography, network design, consensus, and economic incentives.
How Blockchain Works in Cryptocurrency
Cryptocurrency is probably the most famous use of blockchain. Bitcoin, for example, uses blockchain technology to maintain a public record of transactions.
When a user sends cryptocurrency, the transaction is broadcast to the network. Network participants verify it according to the protocol rules. Valid transactions are included in blocks, and accepted blocks become part of the blockchain.
The blockchain helps prevent the same digital asset from being spent twice. This problem, known as double spending, is especially important for digital money because digital information can otherwise be copied.
A blockchain provides a shared transaction history that helps the network determine which transactions are valid. This is a major part of how blockchain works in cryptocurrency.
Other cryptocurrencies may use different blockchain designs, consensus mechanisms, transaction models, and features. Therefore, not every cryptocurrency operates in exactly the same way.
How Blockchain Works in Finance
Financial institutions have shown strong interest in blockchain because many financial processes involve multiple organizations that need to exchange and verify information.
Blockchain may be useful for areas such as cross-border payments, settlement, asset tracking, trade finance, identity systems, and tokenized assets. Instead of several organizations maintaining separate records and repeatedly reconciling them, a shared ledger can potentially reduce duplication and improve transparency.
For example, in an international transaction, several parties may be involved before money reaches its final destination. Blockchain-based systems may help automate certain verification and settlement processes.
However, blockchain is not automatically better than traditional financial databases. Financial organizations must consider privacy, regulation, performance, interoperability, cost, and governance. This is why how blockchain works in finance should be understood as a potential technology solution rather than a universal replacement for existing systems.
How Blockchain Works in Healthcare
Healthcare is another area where blockchain has attracted attention. Hospitals, laboratories, insurance companies, pharmacies, and other organizations handle large amounts of sensitive information.
A blockchain-based system could potentially help different organizations verify certain records and maintain a shared history of data-related activities. It may also support areas such as medical supply tracking, credential verification, consent management, and selected health-record processes.
However, healthcare data requires strong privacy protection. Personal medical information should not simply be placed on a public blockchain where anyone could access it.
For this reason, blockchain healthcare systems may use permissioned networks, encryption, off-chain storage, or other privacy techniques. When discussing how blockchain works in healthcare, it is important to understand that blockchain can support data integrity and coordination, but it does not remove the need for privacy and security controls.
Why Is Blockchain Considered Secure?
Blockchain security comes from several technologies and network rules working together. Cryptographic signatures help prove that transactions were authorized. Hashing helps detect changes in data. Consensus mechanisms help participants agree on valid records. Distributed copies make it harder for one compromised computer to rewrite the entire network history.
However, blockchain should not be described as perfectly secure. Blockchain applications can still have vulnerabilities. Smart contracts may contain programming errors, private keys can be stolen, exchanges can be attacked, and poorly designed networks can have security weaknesses.
The blockchain protocol itself may be strong while an application built around it is poorly protected. Good security therefore requires attention to the complete system, not only the blockchain.
Is Blockchain Really Impossible to Change?
People often describe blockchain as “immutable,” but this term needs some explanation. Once information has been confirmed and added to a well-secured blockchain, changing old data can be extremely difficult because the altered record would conflict with later blocks and the network’s accepted history.
The difficulty depends on the blockchain’s design, size, consensus mechanism, and level of decentralization. A small private blockchain may have very different security characteristics from a large public blockchain.
Therefore, it is more accurate to say that blockchain is designed to make unauthorized changes difficult and detectable rather than simply saying that changes are mathematically impossible in every situation.
Public and Private Blockchains
Not every blockchain works in exactly the same environment. Public blockchains are generally open to participants, although the specific rules vary. Bitcoin and Ethereum are examples of widely known public blockchain networks.
Private or permissioned blockchains restrict participation. An organization or group of organizations may decide who can join the network, view certain information, or validate transactions.
Businesses may prefer permissioned systems when they need greater control over access, privacy, or governance. Public networks may be more suitable when openness and broad participation are important.
This difference is important because how blockchain works depends partly on the type of network being used.
Smart Contracts and Automation
Some blockchain networks support smart contracts. A smart contract is software deployed on a blockchain that can automatically perform actions when predefined conditions are met.
For example, a smart contract might release a digital asset after certain conditions are verified. It can reduce the need for manual processing in some situations.
Smart contracts are commonly associated with decentralized applications, digital assets, finance, gaming, and other blockchain-based services. However, they are still software, which means they can contain bugs or design problems.
Smart contracts can make blockchain systems more powerful, but they also introduce additional technical and security considerations.
Advantages of Blockchain
Blockchain can offer several potential advantages. A shared ledger can reduce the need for different parties to maintain completely separate records. Cryptographic techniques can improve data integrity. Distributed networks can reduce dependence on a single database or administrator. Transparent public blockchains can also make transaction histories easier to inspect.
Another potential benefit is traceability. In supply chains, for example, a blockchain could be used to record selected events as products move between different participants. This can create a verifiable history that may be useful for auditing and tracking.
Blockchain can also support automation through smart contracts. When carefully designed, automated rules may reduce manual work and improve the speed of certain processes.
Limitations and Challenges
Blockchain also has important limitations. Some networks can process fewer transactions per second than traditional centralized databases. Certain consensus mechanisms can require significant computing resources. Storage requirements can grow as blockchain histories become larger.
Privacy is another challenge. A public ledger that makes information transparent may not be appropriate for sensitive business or personal data. Regulations can also create difficulties when blockchain records are difficult to modify or delete.
Interoperability is another issue. Different blockchain networks may use different protocols and data structures, making communication between them difficult.
For businesses, cost and complexity must also be considered. Blockchain should be used when its unique features solve a real problem. Using blockchain simply because it is popular may add unnecessary complexity.
Common Uses of Blockchain
Blockchain is being explored across many industries. Cryptocurrency remains its best-known application, but the technology has broader possibilities.
Financial services can use blockchain concepts for payments, settlement, asset management, and record sharing. Supply chain companies can explore blockchain for traceability. Healthcare organizations may investigate it for data coordination and verification. Governments and institutions can explore applications involving credentials, records, and identity.
Other possible areas include digital ownership, gaming, intellectual property, voting-related research, logistics, insurance, and decentralized applications.
The important point is that blockchain is a technology rather than a single product. Its usefulness depends on how it is designed and applied.
The Future of Blockchain
Blockchain development is continuing, but its future will depend on practical use rather than hype. Organizations are increasingly interested in solving specific problems related to trust, data sharing, ownership, verification, and coordination.
Future blockchain systems may become faster, more energy efficient, easier to connect with other networks, and more user-friendly. Improvements in scalability and privacy could also make some blockchain applications more practical.
At the same time, traditional databases will continue to be useful for many applications. Blockchain is not expected to replace every existing database or technology. Its strongest use cases are likely to be situations where multiple parties need to share a trusted record and where decentralization, traceability, or tamper resistance provides meaningful value.
FAQs
1. What is blockchain in simple words?
Blockchain is a digital record system that stores information in connected blocks and shares the record across a network of computers. It uses cryptography and consensus rules to help protect the record.
2. How does blockchain work step by step?
The basic process is: a transaction is created, shared with the network, verified, placed into a block, approved through consensus, and added to the existing blockchain.
3. How does blockchain work in cryptocurrency?
In cryptocurrency, blockchain records transactions between users. The network verifies transactions and adds valid transactions to blocks, creating a shared history of digital asset transfers.
4. What is a blockchain distributed ledger?
A distributed ledger is a record maintained across multiple network participants instead of being controlled by only one central database. Blockchain is one type of distributed ledger technology.
5. Why are blockchain records difficult to change?
Blocks are connected using cryptographic information, and copies of the ledger may exist across many computers. Changing an old record can therefore conflict with later blocks and the network’s accepted history.
6. Can blockchain be used in healthcare?
Yes. Blockchain can potentially support healthcare applications involving data verification, supply chains, credentials, consent, and coordination between organizations. Privacy and regulatory requirements must be carefully considered.
7. Is blockchain the same as cryptocurrency?
No. Cryptocurrency is one application of blockchain technology. Blockchain can also be used for other types of records, digital assets, verification, and decentralized applications.
8. What is the easiest way for beginners to learn blockchain?
Start by learning four concepts: transactions, blocks, distributed ledgers, and consensus. After understanding these basics, move on to hashes, digital signatures, wallets, validators, miners, and smart contracts.
Final Thoughts
Understanding how blockchain works does not require advanced programming knowledge. The basic process can be explained through a simple chain of events: a transaction is created, the network receives and verifies it, valid transactions are grouped into a block, the network reaches consensus, and the accepted block is connected to previous blocks.
The combination of blocks, cryptographic hashes, digital signatures, distributed ledgers, and consensus mechanisms gives blockchain its distinctive design. Cryptocurrency made the technology famous, but its possible applications extend into finance, healthcare, supply chains, digital ownership, and many other areas.
For beginners, the most important lesson is that blockchain is not simply a database or a cryptocurrency. It is a way of organizing and maintaining records across a network using technical rules that help participants agree on a shared history. Once this basic concept is clear, more advanced subjects such as smart contracts, decentralized applications, tokenization, and different consensus mechanisms become much easier to learn.
If you want to read more interesting and detailed guides, visit EmbossitWorld now. You’ll find useful Information, and a lot of practical information. Don’t miss out.
Add comment